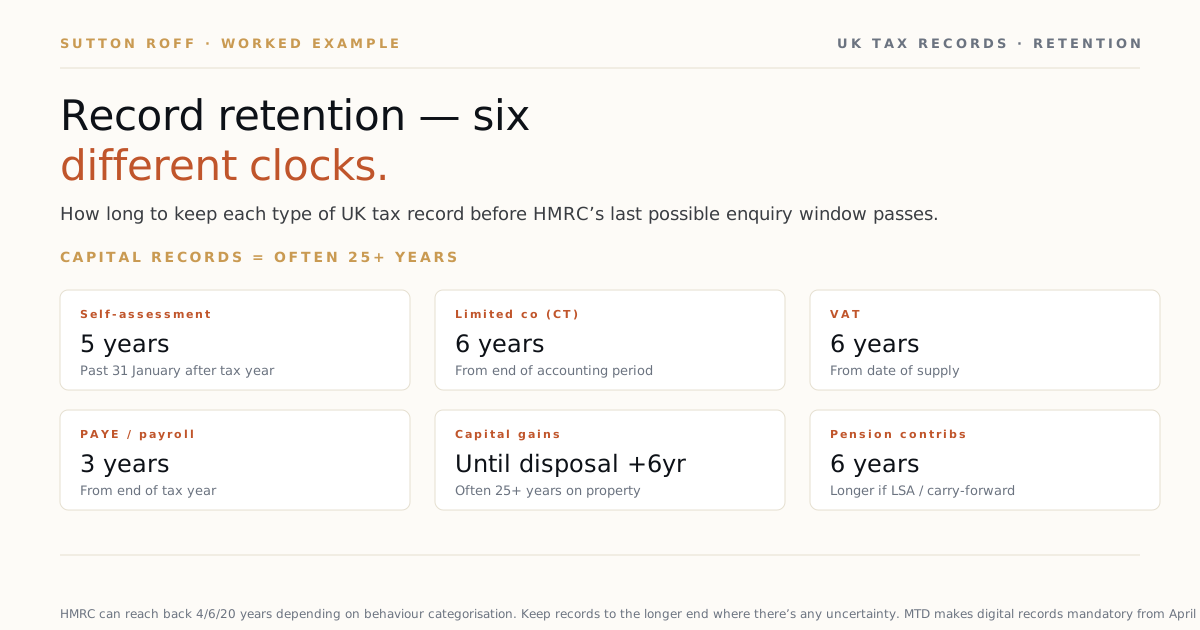
SA records: 5 years past the January after the tax year. Ltd company records: 6. Capital improvement records on property: until you sell plus 4-6 years after — easily 25 years. We see clients shred receipts during enquiries, not realising HMRC’s discovery powers reach back further than the statutory minimum suggests, and not realising property-improvement records save five-figure CGT bills decades later.
The basic time limits — and the asterisk that catches landlords
| Record type | Minimum retention | Practical implication |
|---|---|---|
| Self-assessment (sole traders, landlords, employees) | 5 years from 31 January following the tax year | 2025/26 records: keep until 31 January 2032 |
| Limited company corporation tax | 6 years from end of accounting period | Year-end 31 March 2026: keep until 31 March 2032 |
| VAT | 6 years from date of supply | Older records may be needed if HMRC opens an enquiry |
| PAYE / payroll | 3 years from end of tax year | Plus auto-enrolment pension records: 6 years |
| Capital allowances + CGT base costs | Until disposal + 4-6 years | Long holdings = often 20-30 years of records |
| Pension contributions | 6 years from contribution year | Longer if relating to LSA / carry-forward / tapered AA |
What “records” actually means
The minimum records HMRC expects:
- Bank statements for the relevant period
- Sales records — invoices, till receipts, platform reports
- Purchase records — supplier invoices, receipts
- Expense receipts — for any deduction claimed
- Mileage logs if claiming vehicle costs
- Wage records for any employees
- VAT returns and supporting calculations
- Final accounts and tax computations
You don’t need paper — digital records are accepted. The Making Tax Digital regime requires digital records for VAT (already in force) and is rolling out to income tax from April 2026. So practically, digital is now the norm.
The longer-tail records — capital costs you’ll need 25 years from now
Some records need keeping beyond the standard 5-6 years because they support claims you’ll make later:
Capital improvements on property. The cost of an extension or major refurb reduces the eventual CGT bill on sale. Records of these costs need keeping until the sale plus 4-6 years after — easily 20-30 years for long-held property.
Original purchase costs. The base cost of any capital asset (shares, property, business assets) needs to be kept until the asset is sold. Buy a portfolio in 2010, hold to 2050 — you need 2010 purchase records in 2050.
Pension contribution history. For carry-forward of unused annual allowance (covered in our pension AA piece), you need 4 years of contribution history. For lifetime allowance / Lump Sum Allowance evidence, longer.
Trust and inheritance documentation. Trust deeds, gifts made within 7 years of death, IHT returns — keep indefinitely or until clearly resolved.
What HMRC actually asks for in an enquiry
HMRC’s standard enquiry can request anything supporting the return:
- The return itself and computation working papers
- Bank statements covering the period
- Sales and purchase listings
- Expense receipts (especially over £30 individual)
- Mileage logs
- Capital allowances workings and asset records
- VAT returns and reconciliation if VAT-registered
For a 4-year-back enquiry into a careless error, HMRC can request records back 4 years. For a 6-year careless or 20-year deliberate enquiry, similarly long. Keeping records to the statutory minimum is risky — the statutory minimum reflects when HMRC would normally stop asking, not when they could.
Practical approach: keep digital, keep tagged
For most small businesses and individuals:
- Use accounting software (Xero, QuickBooks, FreeAgent) — keeps records cleanly and meets MTD requirements
- Scan paper receipts immediately — apps like Dext, Receipt Bank capture receipts in seconds
- Cloud storage with year-tagged folders — backup everything important to Drive/Dropbox by tax year
- Keep the SA tax computation — not just the return submitted, but the working figures
- Annual review — at year-end, ensure the year’s records are complete and accessible before moving on
The “shoebox of receipts” approach works for casual hobbyists but breaks once you’re claiming meaningful expenses or facing potential enquiry.
What you can throw away
After the statutory periods, you can dispose of:
- Routine receipts for fully-evidenced expenses
- Bank statements for closed years
- Wage records older than 3 years
- Working papers behind tax returns older than 5-6 years
What you should still keep, even past statutory minimums:
- Original capital asset purchases (until the asset is sold)
- Property improvement records (until the property is sold)
- Pension nomination forms (until updated)
- Final P60 from employment (lifetime — for state pension records)
- Any contract, deed of trust, or partnership agreement still in effect
What about Making Tax Digital
From April 2026, MTD for Income Tax requires sole traders and landlords with income above £50,000 to:
- Keep digital records using HMRC-compatible software
- Submit quarterly updates of income and expenses
- Submit a final declaration each year
From April 2027, the threshold drops to £30,000. The digital-records requirement becomes mandatory for those affected — paper-only records won’t meet the obligation.
We covered the MTD timeline in detail in our MTD for Income Tax piece.
Records during HMRC enquiry
If HMRC has opened an enquiry into a year’s return, you must keep all relevant records until the enquiry concludes — even if that’s beyond the standard 5-year window. Destroying records during an open enquiry can be characterised as obstruction, escalating penalties.
What if you don’t have records?
“I lost the receipts” or “I never kept records” doesn’t end the enquiry — HMRC will use other evidence (bank statements, third-party reports, pattern matching) to estimate the position. Their estimate is usually pessimistic for the taxpayer.
Better to have some records than none. Bank statements alone, even without receipts, give HMRC something to work with that’s usually more favourable than their own estimate.
When this is a bad idea
Don’t shred records “to be tidy” within the statutory window. The few-years-old receipts are exactly what HMRC will ask for in an enquiry.
Don’t rely on the platform/employer to keep records for you. They have their own retention rules and may purge data older than 3-5 years.
Don’t forget about capital-cost records. The eventual CGT calculation needs records that are 20+ years old in many cases.
Key takeaways
- Self-assessment: keep records 5 years past the 31 January after tax year end.
- Limited company: 6 years from end of accounting period.
- VAT: 6 years from date of supply.
- Capital cost records: until asset is sold + 4-6 years after.
- Digital records accepted; MTD makes them mandatory for affected categories.
- During HMRC enquiry, keep records until enquiry concludes regardless of statutory minimum.
FAQ
Do digital scans count as records?
Yes — HMRC accepts digital records including scanned receipts, electronic invoices, and bank-statement PDFs. Originals can be destroyed after digitisation provided the digital copies are clear and complete.
What if I lose records from years ago?
HMRC may use other evidence (bank statements, third-party reports, pattern matching) to estimate. Their estimates are usually pessimistic for the taxpayer. Better to keep records than rely on HMRC reconstructions.
Does HMRC require originals or copies?
HMRC accepts copies (paper or digital) as evidence in most enquiries. Originals can be useful for high-value disputes or where the document’s authenticity is challenged. Digital records with clear metadata are generally fine.
Inherited a chaotic record set or wondering if your bookkeeping meets MTD requirements? Book a free 20-min review — we’ll review your record-keeping setup, digitise where needed, and ensure you’re MTD-compliant before the April 2026 ITSA rollout. Specialist UK Making Tax Digital accountants.