UK creators on any platform — OnlyFans, Patreon, YouTube, Twitch — are self-employed for tax from £1 of profit beyond the £1,000 trading allowance. We see creators incorporate too early (sub-£40k profit, where the Ltd compliance overhead outweighs the saving) or stay sole trader too long (£60k+ profit, where Ltd would save £4,000-£6,000/year). The £50,000 profit line is the rough crossover.
The basics — yes, creators absolutely pay tax
Income from any content platform — subscription tips, custom requests, brand deals, advertising revenue, affiliate commissions — is self-employment trading income. There’s no special “creator economy” tax wrapper.
You register for self-assessment within 5 October following the tax year you started earning. Your tax payments include income tax (at 20%/40%/45% bands beyond the £12,570 Personal Allowance) plus Class 4 NIC on profits between £12,570 and £50,270 at 6%, with 2% above £50,270.
If you cross £90,000 of taxable turnover in any rolling 12 months, you also need to register for VAT (covered in our VAT registration piece). Many higher-revenue creators cross this threshold quickly without realising.
Sole trader versus Ltd — where the £50k crossover sits
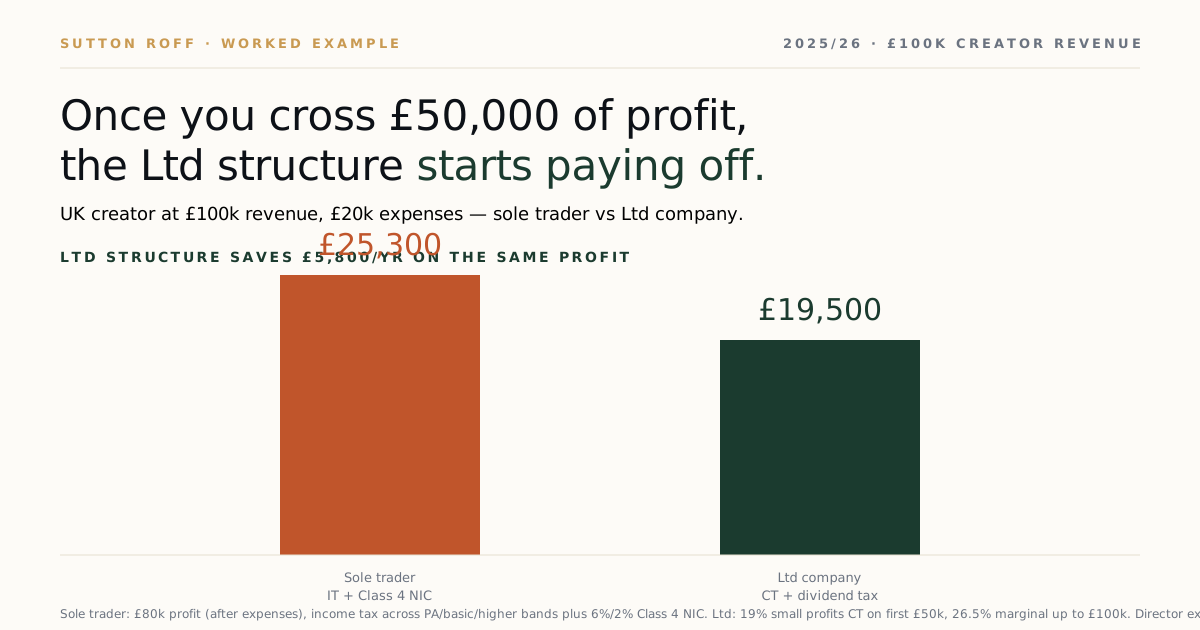
For low and modest creator earnings (sub-£40k profit), sole trader is simpler and roughly equivalent in tax cost. Above £50k of profit, the Ltd structure starts saving meaningful money — by holding pre-tax money in the company at corporation tax rates rather than paying full personal income tax on the lot.
For our worked example (£100k creator revenue, £20k expenses, £80k profit):
Sole trader:
- Profit: £80,000
- Less Personal Allowance: £80,000 − £12,570 = £67,430 taxable
- Income tax: £37,700 at 20% (£7,540) + £29,730 at 40% (£11,892) = £19,432
- Class 4 NIC: £37,700 at 6% (£2,262) + £29,730 at 2% (£595) = £2,857
- Total tax: £22,289
- Plus Class 2 NIC abolished from 2024/25
Ltd company:
- Profit: £80,000
- Director extracts £50,000 via salary £12,570 + dividend £37,430 (basic-rate-band-filler)
- £30,000 retained in company for future use
- CT on £80,000: roughly £15,200 (small profits rate of 19% on first £50k, marginal 26.5% above)
- Personal tax on dividend: £36,930 × 8.75% = £3,231
- Total tax: £18,431
Ltd saves £3,858/year on this profit level, plus the £30,000 retained in company can fund future expenses, pension contributions, or investment without further extraction tax until needed. Compounded over 5+ years the gap widens dramatically.
Expenses creators commonly under-claim
- Equipment — cameras, lighting, microphones, computers, ring lights, monitors. Annual Investment Allowance gives 100% first-year relief.
- Set design / costumes / props — anything used genuinely for content production, deductible against business income.
- Software — editing, scheduling, OBS plugins, Adobe, Canva.
- Subcontractors — editor, virtual assistant, brand deal manager. Pay them properly with invoices.
- Travel — to shoots, conferences, brand events.
- Home office / studio — proportion of bills if a room is dedicated to content production. Or HMRC’s £6/week simplified rate (covered in our home office guide).
- Phone, internet — proportionate use for business.
- Accountancy and legal fees.
- Pension contributions — employer pension if Ltd, personal pension if sole trader.
What’s not deductible: cosmetic procedures, gym memberships, clothing for personal use that “doubles” for content. The wholly-and-exclusively rule applies — content-produced explicitly for sale doesn’t make personal grooming or fitness deductible.
Platform reporting — visible to HMRC since January 2024
From January 2024, online platforms (including OnlyFans, Patreon, eBay, Etsy, Vinted, Airbnb, Uber) report seller activity to HMRC where the seller crosses £1,740 in sales or 30 transactions in a calendar year. The data flows directly to HMRC’s risk-scoring algorithms.
Creators who haven’t been declaring are now visible. The 2024 platform-reporting rules combined with HMRC’s nudge-letter campaigns (covered in our nudge-letter playbook) mean undisclosed creator income is now systematically caught.
If you’ve earned without declaring — voluntary disclosure now is dramatically cheaper than waiting for a letter. Penalties on unprompted voluntary disclosures can drop to 0%; on prompted disclosures (after HMRC writes), they start at 30% and climb based on quality of cooperation.
Brand deals — gifted products and barter
Free products gifted in exchange for promotion are taxable income at market value. A £500 outfit gifted in exchange for an Instagram post: £500 of taxable income (and you can deduct any genuinely-business spending on the post itself).
Barter — “we’ll give you free products if you create content” — is treated as cash-equivalent income. Same logic as the influencer side covered in detail in our influencer PR gifts piece.
The OnlyFans-specific reality
OnlyFans pays creators via SWIFT bank transfer or e-wallet (Cosmo, Paxum). UK-resident creators owe UK tax on the full earnings regardless of the payment method or routing through offshore wallets.
The 20% platform commission is deductible — you only pay tax on net earnings after commission. Most creators record gross earnings and OF commission separately for clean reporting.
Cross-border payment doesn’t change UK tax liability. Currency conversion is at the spot rate on the date of receipt for accounting purposes.
VAT — the £90k question for big creators
UK creator earnings count toward the £90k VAT registration threshold. Cross it in any rolling 12 months and you must register. VAT is charged on UK consumer subscriptions; cross-border subscriptions to non-UK consumers may be outside scope.
For a six-figure-revenue creator, this is a meaningful operational consideration. The VAT impact varies by audience location.
When this is a bad idea
Don’t ignore HMRC platform-reporting expecting they “won’t notice creator income”. They will, and they have.
Don’t try to characterise creator income as a “hobby” once you’ve crossed the £1,000 trading allowance. Above that, it’s trading income full stop.
Don’t incorporate (Ltd) before profits genuinely justify it. Sub-£40k profit creators rarely benefit, and the Ltd compliance overhead adds cost.
Key takeaways
- Creator income is self-employment trading income, taxed via self-assessment.
- Class 2 NIC abolished from 2024/25; only Class 4 NIC on profits above £12,570.
- Sole trader vs Ltd: Ltd typically wins above £50k profit by ~£3-6k/year.
- VAT registration mandatory above £90k taxable turnover.
- Platform reporting from January 2024 — undisclosed income now systematically visible.
- Brand deals and gifted products are taxable at market value.
FAQ
Can I claim cosmetic surgery as a business expense?
Generally no — HMRC’s wholly-and-exclusively rule disallows personal grooming and cosmetic enhancements that have personal benefit beyond the business. Specific exceptions apply for performers (e.g. on stage), but rare for content creators.
Do I need to declare tips and PPV?
Yes — all platform earnings count as income, including subscriptions, tips, PPV (pay-per-view), and PPS (pay-per-stream). Platform fees deducted come off as a business expense before profit calculation.
What’s the difference for OnlyFans creators in Scotland?
Scottish income tax bands differ from England’s: 19% starter rate, 20% basic, 21% intermediate, 42% higher, 47% top rate (2025/26). Higher-earning Scottish creators pay slightly more on the same profits.
Creator profit growing past the £40-£60k zone and you’re not sure whether to incorporate? Book a free 20-min review — we’ll model sole trader versus Ltd at your actual revenue and cost mix, and handle back-period disclosure if you’ve been earning without filing. Specialist UK creator and influencer tax accountants.