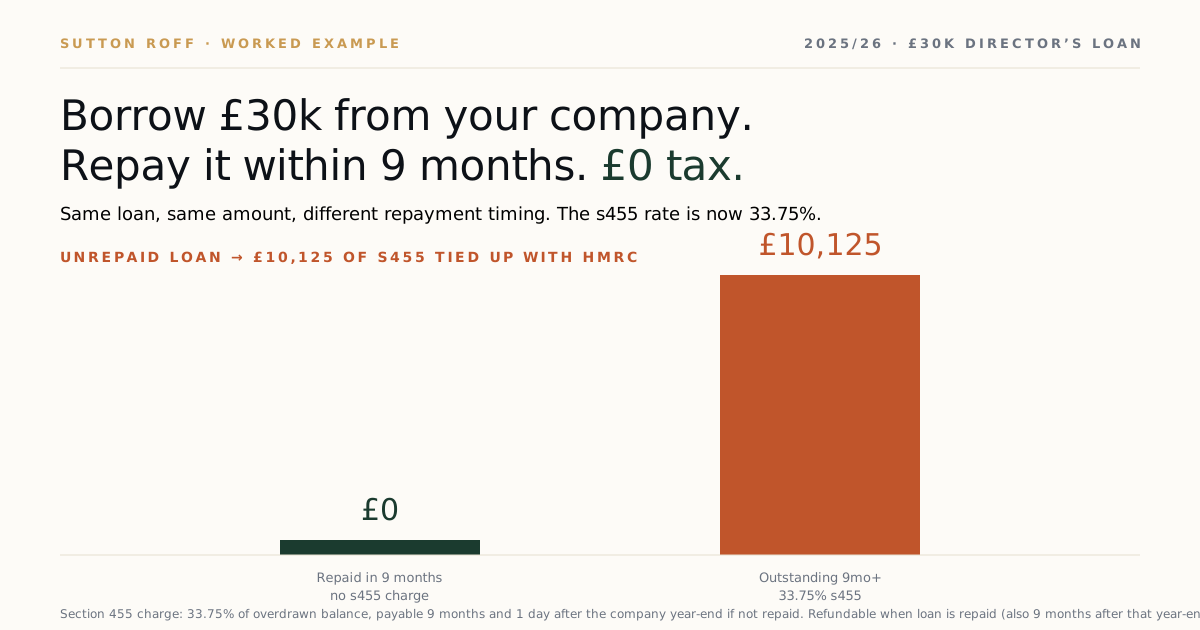
Borrow £30,000 from your Ltd, repay it within 9 months of the year-end, and the cost is £156. Miss that deadline and you owe HMRC £10,125 of Section 455 tax — refundable when you eventually repay, but locked up for 18-24 months in the meantime. We see directors stumble into this not realising the s455 rate jumped from 32.5% to 33.75% in 2022 to align with higher-rate dividend tax.
The Director’s Loan Account in plain English
Every Ltd company maintains a Director’s Loan Account (DLA) — a running ledger of money owed between the director and the company. The DLA goes:
- Overdrawn (director owes the company): you’ve taken money out personally beyond your salary or declared dividends
- In credit (company owes you): you’ve put personal money into the company, or paid expenses personally that the company hasn’t reimbursed yet
An overdrawn DLA at the company year-end is “borrowing from the company”. Whether this triggers tax depends on how long the loan stays overdrawn.
The s455 charge — and why it’s 33.75% now
If a director-shareholder’s DLA is overdrawn at the company year-end and remains overdrawn 9 months and 1 day later, the company pays a Section 455 charge of 33.75% of the overdrawn balance to HMRC.
The rate jumped from 32.5% to 33.75% to align with the higher-rate dividend tax — HMRC’s rationale being that an unrepaid director’s loan is, in substance, a disguised dividend extraction. Aligning the rates removes the incentive to use loan-and-write-off as a backdoor dividend route.
The s455 charge is refundable when the loan is repaid. So if you borrow £30,000 in year 1, pay the £10,125 s455 charge by 9 months after year-end, then repay the loan in year 3, the £10,125 is refunded by HMRC. The catch: the refund comes 9 months after the year-end of the year of repayment — so you’re typically out of pocket for £10,125 for 18-24 months.
The interest BIK on loans above £10,000
Separate from s455: if your DLA exceeds £10,000 at any point in the tax year, HMRC charges a benefit-in-kind on the “deemed interest” — calculated as the loan balance × the official HMRC interest rate (2.25% for 2025/26).
For a £30,000 loan held all year:
- BIK on £30,000 × 2.25% = £675
- Higher-rate director income tax: £675 × 40% = £270/year
- Plus Class 1A NIC for the company: £675 × 15% = £101/year
If you actually pay interest to the company at the official rate, the BIK is eliminated. The interest paid by you is taxable income for the company (£675 × 19% CT = £128 tax). Some directors prefer to pay the interest to avoid the BIK — most prefer to absorb the £270 BIK as it’s simpler.
Owen’s £30,000 loan — repaid in time versus left outstanding
Owen, a Ltd director, borrows £30,000 from his company on 15 March 2025. Company year-end is 30 June 2025. DLA is overdrawn by £30,000 at year-end.
| Outcome | Repaid within 9 months | Outstanding 9+ months |
|---|---|---|
| s455 charge (33.75% of balance) | £0 | £10,125 |
| BIK on interest (loan > £10k) | £156 (one-off, pro-rata) | £270/yr ongoing |
| Cash with HMRC | None | £10,125 locked up 18-24 months |
| Total cost on £30k loan | £156 | £10,395+ first year |
The bed-and-breakfast anti-avoidance — repaying then re-borrowing fails
HMRC noticed directors repaying loans in the last week of the 9-month window, then re-borrowing the same amount in the first week of the new year — neatly resetting the s455 clock without any real repayment. The “bed and breakfast” anti-avoidance rule (CTA 2010 s464C) catches this.
The rule: if a loan is repaid and a new loan of £5,000+ taken from the same company within 30 days, the repayment is matched against the new loan rather than counting as repayment of the old one. So the bed-and-breakfast trick fails.
To repay genuinely: the repayment must be from external sources (personal savings, dividend declared, salary credited) and must not be followed by an immediate re-borrowing.
Three legitimate ways to clear an overdrawn DLA
1. Pay it back from personal funds. Cleanest. Director transfers cash from personal account to company account. DLA balance reduces.
2. Declare a dividend. Company declares a dividend to the director equal to the overdrawn amount. Dividend triggers personal tax (£500 allowance, then 8.75/33.75/39.35%) but the DLA is reduced. Often the right answer for higher-rate directors who’d be paying dividend tax anyway.
3. Increase salary. Company pays additional salary, with PAYE and NIC, to clear the DLA. Higher tax cost than dividend route for most cases.
Many directors clear the DLA on the date of the year-end accounts being signed — declaring a dividend at that point with effect of clearing the DLA balance.
Loan write-off — be careful
If the company “writes off” a director’s loan (forgives the debt), the written-off amount is treated as a distribution to the director — taxable as a dividend. This is identical to declaring a dividend, except the company doesn’t get to refund the s455 paid (HMRC doesn’t refund s455 on written-off loans, only repaid loans).
So writing off a £30,000 loan after paying £10,125 of s455 = director pays dividend tax on £30,000 (potentially £10,000+) AND the company loses the £10,125 forever. Worst-case combination.
The micro-loan exemption
Director’s loans under £10,000 in aggregate at any point in the tax year don’t trigger the BIK on interest. But the s455 charge still applies if the DLA is overdrawn at year-end and remains so 9 months later — even on small amounts.
So a £8,000 short-term loan: no BIK, but if it’s still outstanding at year-end + 9 months, £2,700 of s455 is due. Useful to know when planning small advances.
When this is a bad idea
Don’t borrow a substantial amount without a repayment plan. The 9-month window is short.
Don’t try to bed-and-breakfast a loan to dodge s455 — anti-avoidance catches it.
Don’t write off a loan to “clean up” the balance sheet without modeling the dividend tax + s455 loss. Repay or declare dividend instead.
Don’t mix personal and company spending through the company card without proper DLA tracking. Sloppy bookkeeping creates surprise s455 charges that could have been avoided.
Key takeaways
- Director’s Loan Account: overdrawn = director borrowed; in credit = director lent.
- Overdrawn at year-end + 9 months = 33.75% s455 charge on the balance.
- s455 is refundable when loan is repaid (refund takes 9+ more months).
- Loans above £10,000 trigger BIK at 2.25% × balance × marginal rate.
- Bed-and-breakfast anti-avoidance: 30-day re-borrow rule.
- Repay by external funds, dividend declaration, or salary — not by writing off.
FAQ
Can I roll over a director loan year-on-year?
Repaying then immediately re-borrowing within 30 days fails (bed-and-breakfast anti-avoidance). Genuine sustained borrowing across multiple years works, but s455 keeps applying. Consider clearance via dividend declaration or repayment from external funds.
What about lending to a connected family member?
Loans to participators’ associates (close family members of shareholders) can also trigger s455 in some cases. The rules are anti-avoidance focused — don’t use a relative as a pass-through to avoid the charge.
How is interest on the loan calculated?
For BIK purposes, HMRC’s “official rate” (2.25% in 2025/26) applies to balances above £10,000 throughout the year. Either pay actual interest at this rate (deductible for the company) or absorb the BIK on the difference.
DLA gone overdrawn and the year-end is approaching? Book a free 20-min review — we’ll size the s455 exposure, structure clearance via dividend declaration or repayment from external funds, and avoid the bed-and-breakfast trap. Specialist UK Ltd director accountants.